
Gerald - Cash Advance
- Rating
- 4.4
- Downloads
- 500.00K
- Content Rating
- Everyone
Gerald - Cash Advance - Screenshots
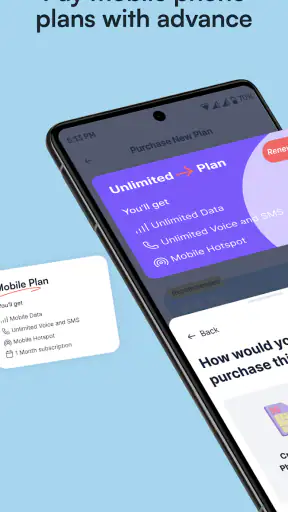
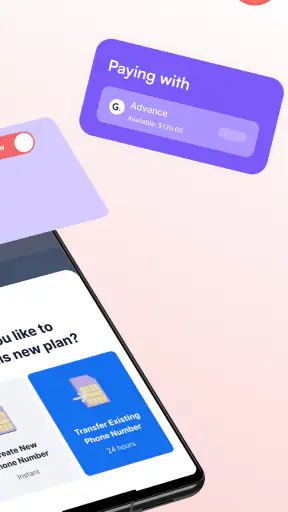
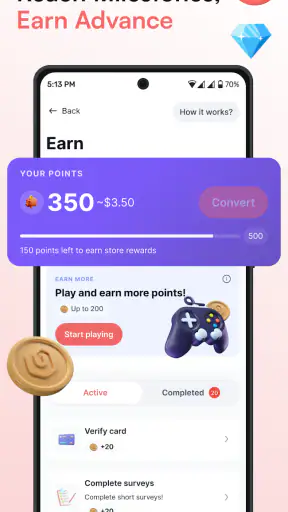
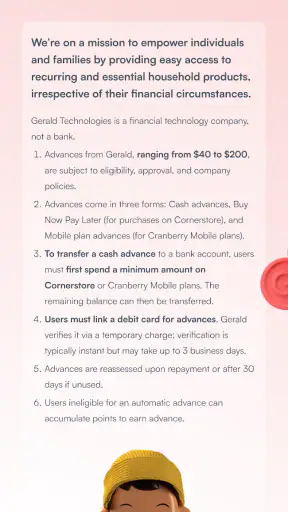
Pros
- Simple application process with clear steps for requesting an advance.
- May provide quick access to funds for eligible users.
- Useful repayment reminders can help users track upcoming due dates.
- Mobile-friendly design makes account management convenient on the go.
- Transparent eligibility details help set expectations before applying.
Cons
- Availability and terms may vary by state and individual eligibility.
- Advance fees can make borrowing expensive for short-term needs.
- Late repayment may lead to additional fees or account restrictions.
- Not a replacement for stable income or long-term financial planning.
- Requires sensitive personal and financial information during registration.
Gerald - Cash Advance - Description
- App Name
- Gerald - Cash Advance
- Package Name
- com.geraldwallet
- Developer
- Gerald Technologies, Inc.
- Category
- Finance
- Last Updated
- Jul 8, 2021
- Version
- 69.0.5
When an unexpected expense lands between paydays, the problem is usually not long-term budgeting. It is the awkward gap between needing a small amount now and having money arrive later. Gerald - Cash Advance is built around that situation. It is a free finance app from Gerald Technologies, Inc. that presents cash advances without a credit check or interest, making it more relevant to short-term timing problems than to ordinary banking.
I approached it as a practical emergency tool rather than a replacement for a bank account. That distinction matters. An advance can help when a bill, transport cost, or essential purchase cannot wait, but it does not remove the underlying expense. The useful question is whether the app makes that short bridge simple enough, and predictable enough, to justify adding another financial service to your routine.
From a cash shortfall to a completed advance
Starting with the right kind of problem
The best starting point is a clearly defined, limited need. Imagine checking your balance before a work commute and realizing that a necessary expense will arrive before your normal income. In that moment, the appeal of Gerald is easy to understand: the service is aimed at fast access to cash, and the store summary specifically emphasizes no credit check and no interest.
I would not begin by treating the app as spare income. The sensible use is a one-off bridge with a repayment plan already in mind. Before opening it, I would write down the amount needed, the date money should become available again, and the expense that cannot reasonably be delayed. That small preparation prevents the common mistake of requesting money simply because it is visible.
Because the app is listed as free and carries an Everyone content rating, it is approachable for a broad audience. It is available for Android devices running version 7.0 or later, which also means that people using older phones should check compatibility before planning around it. The current version is 69.0.5, so keeping the installation updated is a sensible first step when dealing with a finance app.
What the first setup is really for
The opening experience should be viewed as a handoff between the app and your financial information. A cash advance service needs enough context to determine whether the request can move forward, so I would read each screen carefully rather than tapping through quickly. Names, account details, income timing, and permissions are not minor formalities here; they affect whether the request can be evaluated and how money can reach you.
My practical advice is to use the financial account that best reflects your everyday cash flow, not an account that is rarely used. If the app has trouble understanding where regular money arrives, the process can become less useful even when your overall finances are stable. I would also make sure the account is active and that the information entered matches the account holder details exactly.
This is one of the less glamorous parts of the workflow, but it is where many finance tools create friction. The promise of speed only helps if the information exchange is clean. A user who is uncomfortable connecting financial information should pause and decide whether the convenience is worth that trade-off. A traditional bank conversation or a familiar budgeting method may feel slower, but it can offer a more comfortable relationship for someone who does not want another app involved in their finances.
Moving from request to review
Once the account side is ready, the next handoff is from your request to the service’s assessment. The important mindset is not to assume that seeing an application screen guarantees immediate money. A request still has to pass through the app’s process, and the outcome can depend on the information available to it.
I would review the requested amount twice before submitting. The right amount is the smallest one that solves the immediate problem. Asking for extra room can make the later repayment feel heavier, while asking for too little can force a second search for money. This is a simple but valuable workflow improvement: define the expense first, then use the app, rather than browsing for an amount without a specific purpose.
The absence of a credit check is particularly relevant for people whose credit history does not reflect their current ability to manage a small short-term need. It does not mean every request will automatically work, and it should not be read as a guarantee of approval. I see it as a change in the type of gatekeeping involved, not as a promise that the normal checks disappear.
Where the handoffs matter
There are several points where responsibility moves between you, the app, and the financial account connected to it. You supply accurate information. Gerald processes the request. The linked account becomes part of the route through which the advance and later repayment are handled. Each handoff can introduce delay or confusion if details do not line up.
This is why I would avoid starting the process during a rushed moment, such as standing in a checkout line with a payment already failing. If the app asks for clarification or the connected account does not behave as expected, stress makes it harder to distinguish a temporary issue from a genuine eligibility problem. Starting a little earlier, when the expense is known but not yet urgent, gives you time to choose another solution if the workflow stops.
Another useful habit is to keep a written note of what you requested and when you expect the money to be available. That note is not a Gerald feature; it is a personal control that keeps the app from becoming a black box in your budget. I prefer financial tools that show me the next action clearly, but I still want my own record outside the app.
Getting to the result
If the request completes successfully, the result is straightforward: access to cash intended to cover the shortfall. The no-interest positioning makes the cost easier to understand than a product that grows through interest charges, but I would still inspect the final screens and any terms presented before relying on the money. “No interest” is useful language, yet the complete financial picture is always more important than one attractive feature.
The outcome is strongest when it solves a defined problem without changing the rest of the month. For example, covering a necessary trip to work can protect income, while using the same tool for an impulse purchase simply moves the pressure forward. I would ask myself whether the advance protects something important or only postpones a decision. That question is more valuable than the speed of the request itself.
After receiving an advance, I would immediately adjust my spending plan for the next incoming payment. Treating the future balance as already committed prevents the classic cycle in which a short-term solution creates another shortfall. Gerald can help with timing, but it cannot make a tight budget spacious. The app works best when the user remains actively involved in the repayment side of the decision.
Where the flow can break
The biggest weakness of any fast-cash workflow is that “fast” is not the same as “certain.” A request may not produce the result you want, or the account connection may require extra attention. That uncertainty matters if the expense has a firm deadline. I would never make the app my only plan for rent, utilities, medicine, or travel that cannot be missed.
Another breaking point is the temptation to repeat advances. A tool designed for an occasional gap becomes risky when it is used to cover ordinary spending every pay cycle. If the same shortfall appears again and again, the better answer is usually a conversation with the bill provider, a change to recurring expenses, a structured budget, or a more conventional credit product with clearly understood terms.
People who need a larger, longer-term amount should also look elsewhere. A cash advance is naturally suited to a narrow bridge, not a major purchase or a debt that will take months to manage. A bank loan, credit union product, employer-based option, or carefully compared credit card may be more appropriate in that situation, even if those alternatives involve more screening or different costs.
How it compares with familiar alternatives
Compared with overdrawing a bank account, Gerald’s appeal is the chance to address a shortfall before a payment fails rather than waiting for the bank to react afterward. An overdraft may be automatic, but it can also be difficult to understand in the moment. The trade-off is that Gerald requires you to open the app, provide information, and move through a request instead of relying on an existing banking relationship.
Compared with a credit card, the no-interest approach may be easier to reason about for a small, short-lived need. A credit card can be more flexible for purchases and may already be accepted everywhere, but carrying a balance can become expensive depending on the account terms. Gerald is more focused: it is for access to cash, not an open-ended spending line.
Compared with borrowing from a friend or family member, the app offers a more private and formal route. That can be valuable when asking someone close to you would be uncomfortable. On the other hand, a trusted person may offer more flexibility about timing, while an app-based arrangement keeps the process tied to its own rules and account workflow.
Compared with a payday loan, the stated absence of interest makes Gerald look considerably more attractive for the narrow use case it targets. Still, I would not compare products by headline wording alone. Read the complete terms, understand what you are agreeing to, and confirm how the repayment fits your next payment cycle. A product can be less expensive than an alternative and still be a poor choice if it encourages repeated borrowing.
Who will get the most from it
I think Gerald is most useful for someone with a predictable incoming payment, a small temporary gap, and a specific essential expense. The app’s value is not that it transforms a person’s finances. Its value is that it may help a user navigate an inconvenient few days without relying on a credit check or interest-bearing balance.
It can also suit someone who prefers handling a request privately on a phone instead of making a call or visiting a branch. The mobile format keeps the process close to the moment of need, although that convenience should be balanced against the responsibility of reviewing every step. A fast interface is helpful only when the user remains deliberate.
I would be more cautious recommending it to someone whose income date is uncertain, whose account regularly runs short, or who already uses several borrowing services. In those situations, another advance may hide a structural problem. The better next move could be debt counseling, a spending review, an employer conversation, or a more stable financial product.
What the app’s reception tells me
Gerald has reached over 500 thousand installs and holds an average rating of 4.4 from around 10 thousand ratings, with roughly 4.2 thousand written reviews. That level of adoption suggests that the basic idea resonates with many people who want a mobile answer to short-term cash pressure. It is useful reassurance, but it is not a substitute for deciding whether the workflow fits your own situation.
The developer, Gerald Technologies, Inc., has kept the product in the finance space rather than presenting it as a general shopping or banking app. That focus is helpful because the purpose is easy to understand: start with a cash gap, move through an account-based request, and aim for a short-term outcome. The focused purpose is also the main limitation, since users looking for full budgeting, investing, or everyday banking tools should not expect this app to replace them.
My practical verdict after following the workflow
I see Gerald as a useful emergency option when the need is small, the timing is clear, and the user has already considered how the next incoming money will cover the advance. The no-credit-check and no-interest positioning addresses two common concerns, while the free download lowers the barrier to trying the service. Those strengths make it worth considering for a narrowly defined cash-flow problem.
My recommendation comes with a firm condition: use it as a bridge, not as a routine. Begin with the expense, check the account information carefully, request only what solves the problem, and keep your own record of the expected repayment impact. If the process stalls, do not keep pressing simply because the original expense feels urgent; switch to a backup plan.
For someone who needs a larger loan, wants comprehensive money management, or has recurring difficulty making it to the next payment, a bank, credit union, budgeting service, or debt-support option may be the better path. For the person facing one manageable timing gap, Gerald can be a practical tool—as long as its convenience does not replace sound judgment.
FAQ
What is Gerald - Cash Advance, and how does it work?
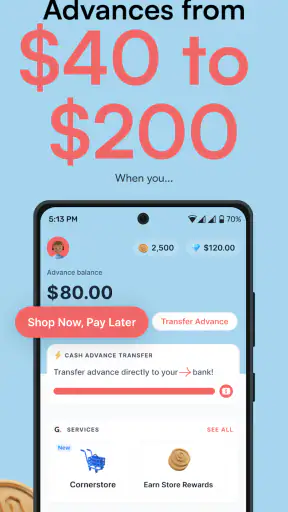
Gerald is a financial app that may provide eligible users with access to an interest-free cash advance, often described as a way to receive part of an upcoming paycheck before payday. After creating an account, you typically connect a supported bank account, verify your information, and review the amount available to you. Approval, advance limits, and transfer speed depend on Gerald’s eligibility requirements and your account activity.
How much money can I borrow through Gerald, and are there any fees?
The amount available through Gerald is not the same for every user. Your initial limit may be modest and can change over time based on factors such as account history, income information, and repayment behavior. Gerald generally promotes fee-free or low-cost access compared with traditional payday loans, but optional expedited transfers, subscription features, or other services may have charges. Always check the final terms shown in the app before confirming an advance.
How quickly will I receive a Gerald cash advance?
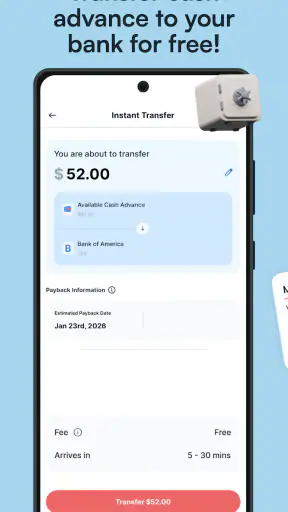
The delivery time depends on the transfer method you select and the bank account or card connected to your Gerald profile. Standard transfers may take longer, while an instant option, when available, could arrive sooner but may involve an additional fee or eligibility conditions. Bank holidays, verification reviews, and incorrect account details can also cause delays, so the app’s estimated arrival time should be treated as an estimate rather than a guarantee.
What are the repayment rules for a Gerald advance?
A Gerald advance is generally expected to be repaid automatically from a linked bank account on or around your scheduled repayment date. Before accepting the money, review the repayment amount, date, and account that will be charged. Make sure sufficient funds are available, because a failed payment may lead to restrictions, additional bank charges, or difficulty receiving future advances. Repayment policies can change, so consult the current in-app agreement.
Is Gerald - Cash Advance safe, and who can use it?
Gerald may be useful for eligible adults who need a small short-term advance, but access is not guaranteed and the service may only operate in selected locations. The app can request personal, banking, and identity information to evaluate eligibility and provide its services, so download it from an official store and review its privacy policy carefully. It should not replace an emergency fund or be used repeatedly to cover ongoing financial shortfalls.


